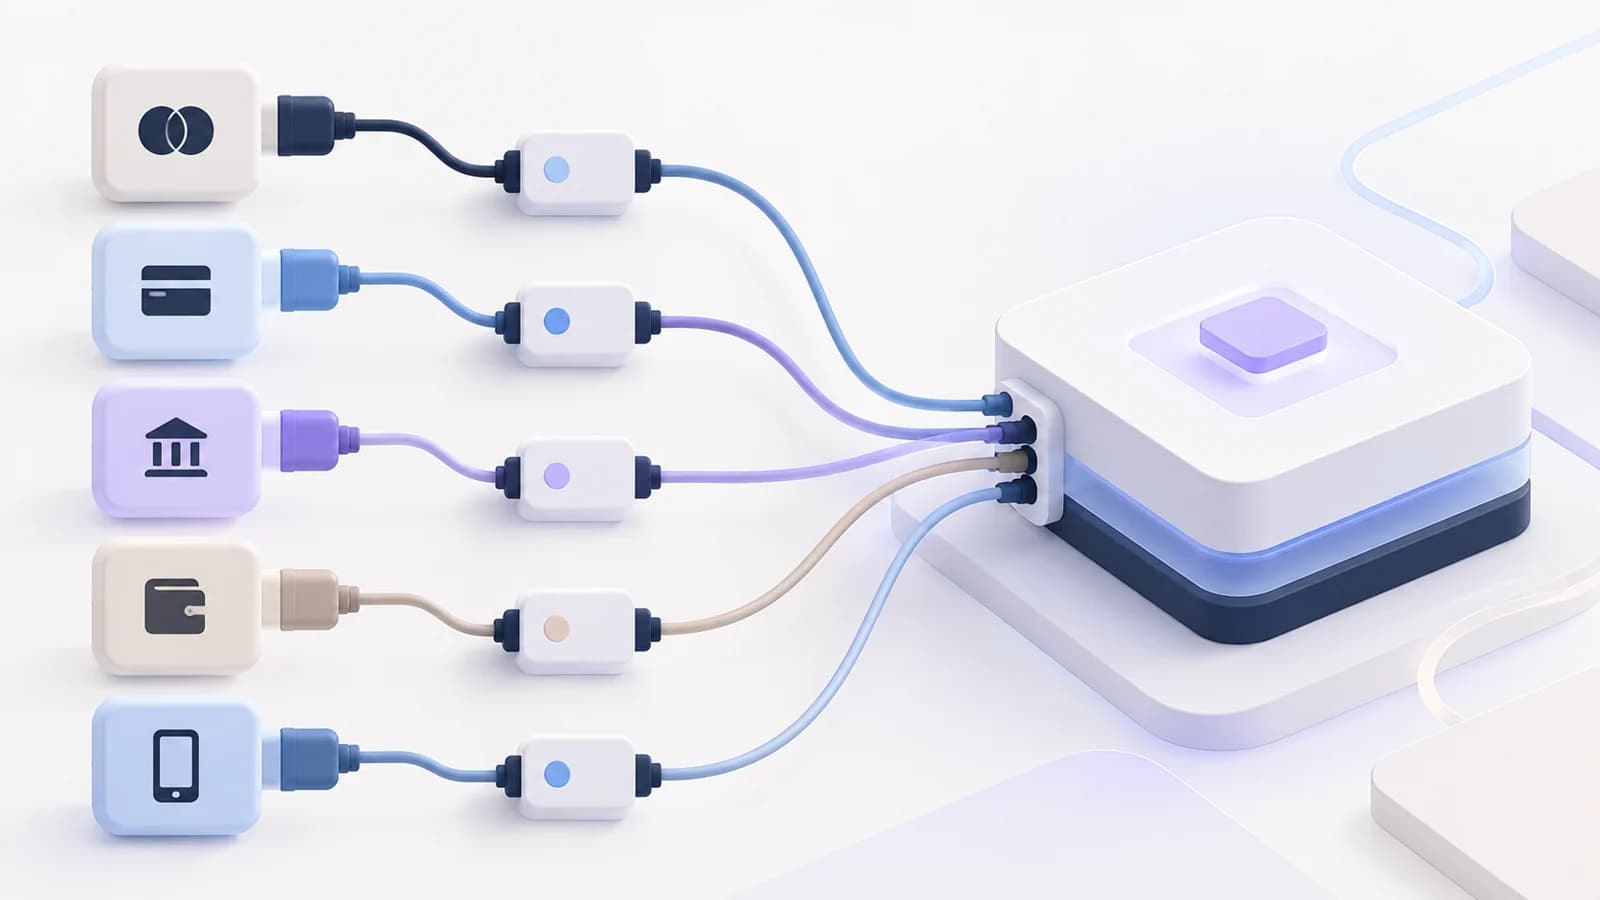
Payment orchestration is the layer that coordinates how payment requests move across payment providers, methods or routes.
What orchestration can coordinate
- provider selection or routing;
- payment-method availability;
- provider-specific request and response mapping;
- payment-state normalization;
- fallback to another approved route where safe;
- common reporting and reconciliation inputs.
What orchestration does not automatically mean
It does not automatically mean the orchestrator holds funds, acts as merchant of record, owns the customer's subscription or has authority to debit every payment method.
Orchestration and billing are different layers
Billing decides what is due and when. Orchestration decides how an eligible payment attempt is routed and represented across providers.
A product can combine both capabilities, but the concepts remain useful to separate.
Why it matters in multi-provider markets
When merchants need different PSPs, wallets or country setups, orchestration can keep the merchant-facing payment contract more stable while provider-specific details change underneath.
Orchestration can operate at several levels
Some systems mainly route a payment request to one processor or another. Others also normalize status, manage provider credentials, retry provider calls or expose one merchant-facing API across markets. The exact scope depends on the product.
A routing example
A Kenyan merchant may have one PSP route for M-PESA and another for a card processor. An orchestration layer can decide which provider receives an eligible attempt and translate the result into a common payment state.
The billing system still decides whether the invoice is due, whether another attempt is allowed and whether recovery should stop after payment.
Questions buyers should ask
- Does the orchestrator ever hold or settle funds?
- Which licensed providers sit underneath it?
- How are provider outages and fallback handled?
- Does switching provider preserve merchant references and reconciliation evidence?
- Which business states remain the merchant's responsibility?
Those questions reveal whether the product is mainly a routing abstraction, a broader payments platform or part of a billing stack.